Sign in. It’s quick, free and it’s up to you.
An account is an optional way to support the work we do. Find out more.
Sign in. It’s quick, free and it’s up to you.
An account is an optional way to support the work we do. Find out more.
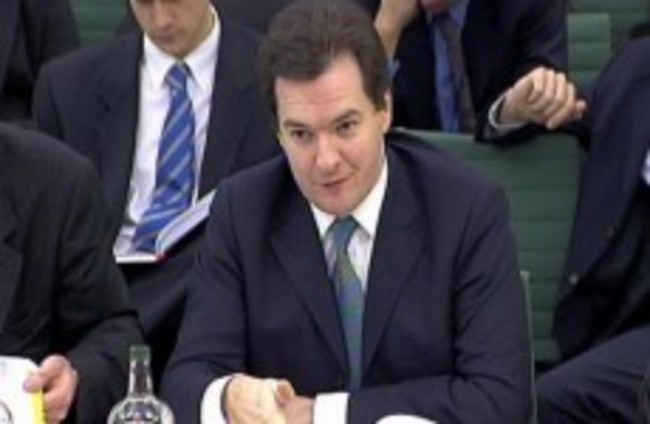
BRTIAIN’S CHANCELLOR OF THE EXCHEQUER George Osborne will publish legislation seeking approval for the UK’s bilateral €3.87bn loan to Ireland from the House of Commons today.
According to the Guardian, the legislation will cap the loan and introduce measures allowing further increases via a vote in parliament.
Osborne said that the Irish loan is a special case and he has “given the strongest possible hint” that Britain will not make loans to other EU members.
The interest rate on the €3.87bn loan is still subject to negotiation, but Osborne has indicated that it will fall within the rate bands set by the EU and IMF. The loan will be reviewed every six months and the IMF will primarily track loan payments.
The Irish Times reports that Britain is lending about €8bn overall to Ireland, through the bilateral loan and funds pledged to the IMF and the EU’s stability fund.
Osborne said Ireland was paying the price for failing to regulate its banks properly, but was not the only one in Europe to have done so.
Daily Mail reports that the cost to British taxpayers will exceed initial estimates and could rise to £7 billion Treasury officials said Britain would charge Ireland an interest rate on the loan of between 5.7 per cent, the rate at which the IMF and the EU are charging, and 6.05 per cent, the interest rate imposed by a separate Eurozone-only fund.
Sweden’s finance minister recently said he believed Sweden, Denmark, Norway and Switzerland were all willing to provide bilateral loans to Ireland, and the Dutch government recently approved the Dutch part of Ireland’s bailout.

To embed this post, copy the code below on your site




have your say