Sign in. It’s quick, free and it’s up to you.
An account is an optional way to support the work we do. Find out more.
Sign in. It’s quick, free and it’s up to you.
An account is an optional way to support the work we do. Find out more.
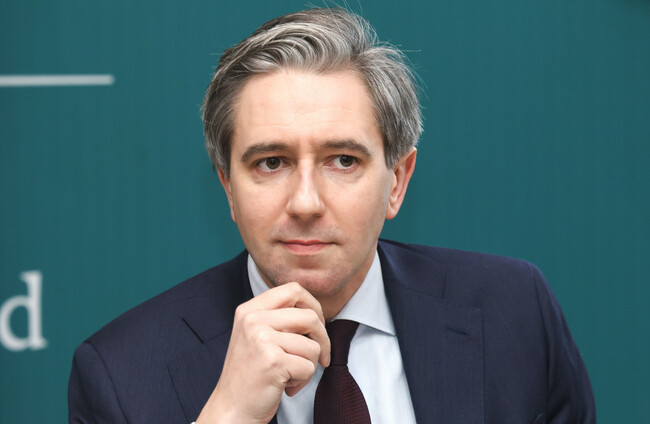
FINANCE MINISTER SIMON Harris has shared more details about the new state-backed investment scheme.
Announcing Budget 2027 in the Dáil, the Fine Gael leader said Irish people have a strong culture of saving, yet participation in investments remains very low.
He said investing can be complex, inaccessible and “something that is reserved for those with significant wealth or significant expertise”.
“We, as a government, want to change that.”
We’ve known a few details about the new personal investment account for a while now, since Harris flagged that it was in the works earlier this year, but many of the blanks were filled in this afternoon.
The new account will be available to any Irish tax resident over the age of 18, with one account permitted per person.
Harris confirmed that it will open on 1 July 2027 and will be legislated for in the Finance Bill.
The account will have a tax-free threshold of €50,000, meaning the first €50,000 in the account will never be subject to tax.
A flat tax rate of 1% will apply to the value of the account above that threshold, not just any profit or loss that it makes over a year.
It’s fair to say that this is at the more generous end of what was expected. Some experts had expected a tax-free threshold of around €20,000.
The €50,000 threshold means that, for example, if the account is valued at €2,000 above the threshold at €52,000, the tax payable for that year would be €20.
The maximum amount that people will be able to put into the account in a year will be €12,000, which works out at €1,000 per month. There will be no minimum contribution.
“If you deposit €12,000 a year into an account over three years, and that deposit increases in value by 5% or 10%, you still won’t hit the €50,000 capital balance in your account, so you will not pay any tax,” Brian Murphy, tax partner at Grant Thornton, told The Journal.
The accounts will operate outside the scope of taxes that currently apply to different investment products, meaning capital gains tax, dividend withholding tax, investment undertaking tax or life assurance exit tax will not apply.
Deemed disposal also will not apply to the new account.
There will be no requirement for people to engage with Revenue to provide a tax return. The responsibility for the administration of the account will fall on the account provider, which could be a bank, investment firm or insurer.
Anyone who chooses to open an account will be able to invest in shares, bonds and exchange-traded funds (ETFs) – a specific type of fund which allows buyers to track the performance of a group of shares.
Murphy told The Journal that these different products and how the money is ultimately invested will be explained by the provider to the investor, who will then choose which account they feel they will get a better return from.
“If you take an individual who’s depositing €2,400 a year for a period of five years, you’ve put around €12,000 in your accounts at that point. You’re still well below the €50,000 threshold,” he said.
“The value of your investment may rise or fall, of course, but you wouldn’t expect an investment of that amount to rise to €50,000 in that period, so there will be no tax payable until you have capital of €50,000 in the accounts.”
A new national financial literacy strategy will be rolled out to help people develop their knowledge of and confidence in investments before the accounts go live.
The Competition and Consumer Protection Commission (CCPC) has launched new online resources on savings and investments, which includes a self-assessment tool for those considering investing.
Harris said deposit and savings accounts will continue to be the right choice for many people and for many purposes, as well as state savings.
Murphy said the primary reason someone might choose to open an investment account over a savings account in a bank is due to the latter providing a very low interest rate return.
“Individuals who have money sitting in normal savings accounts in banks, in a lot of cases, the interest rate that they are getting on their money is actually less or very close to the rate of inflation,” he said.
“The argument would be that people who have money sitting in normal savings accounts are actually losing money in terms of the real value of your cash, because the rate of inflation is sometimes even higher than the interest rate that you are getting.”
He said the investment accounts will give people the ability to invest in accounts that are themselves using the money to invest in equities or shares, where while there is risk attached, there is the potential for a more significant gain over a period of time.
“Over long term, there would be a hope that individuals would see a larger increase in the value of their money in these accounts than they would if they simply had it sitting in cash or in a normal savings account.”
Harris said changing Ireland’s investment culture will not and should not take place overnight.
“But I truly believe that this can be a moment we will look back on and say that that was the day we democratised the long-term gains from investment, and we ensured that more benefits were felt by far more of our people.”

To embed this post, copy the code below on your site




have your say